How to give money so it isn't gone by Monday
09/10/2026 · The Hero of the Book Team
Card, transfer or an account in the child's name? How to give money so some of it lasts, when investing pays off and what to write for an 18th.
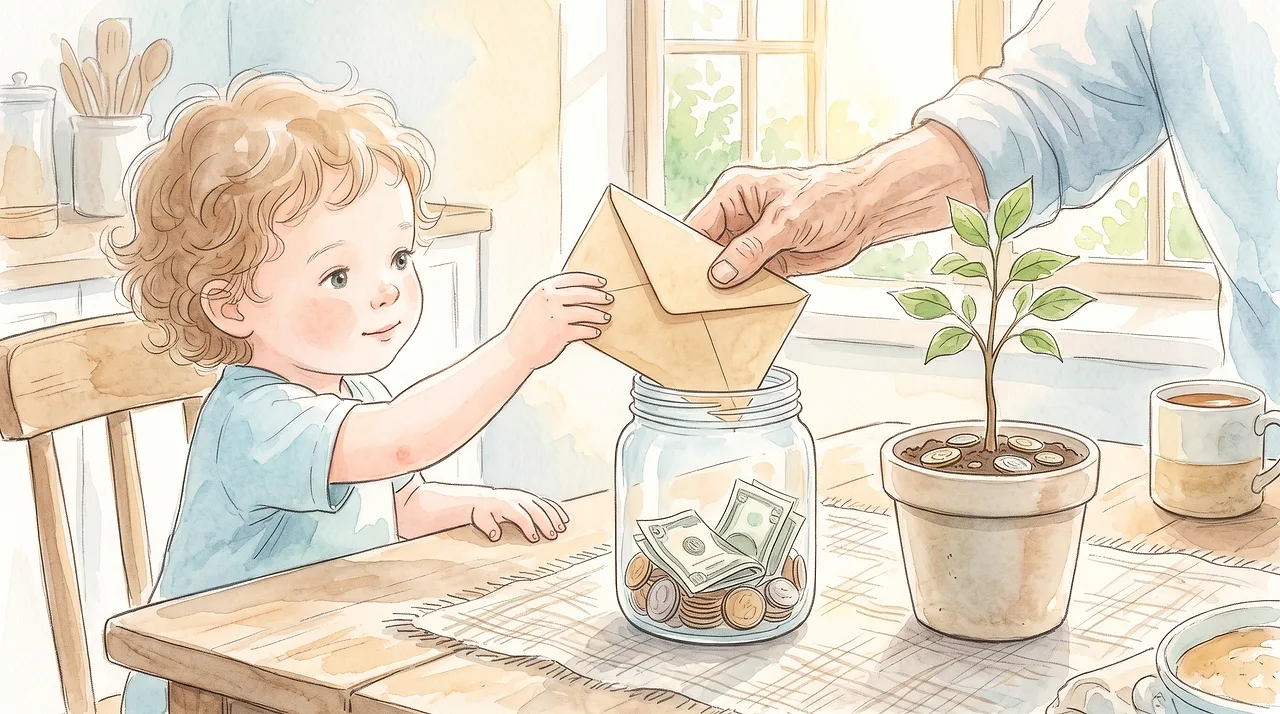
Give money with a clear purpose and a clear path: a small amount for spending can go in a card, a bigger sum is better as a bank transfer to the person's own account, or into a savings or investment account in their name. Add a few lines about what the money is for — a purpose written on paper holds money together better than any bank. An investment account instead of an envelope makes sense when the amount is larger and the child won't need it for at least five to ten years.
Envelope, transfer or an account in the child's name
How you hand money over decides how quickly it melts away. Cash is the most personal and the fastest spent; an investment is the slowest and the most distant. Each route suits something different.
| Method | Best for | Drawback |
|---|---|---|
| Cash in a card or envelope | a small amount for a specific treat, a child under ten who is learning to pay for things | spent fastest, easily lost among the other presents |
| Bank transfer to their account | teenagers and adults who already have their own account | without a note it feels like a pay packet, not a present |
| Savings account in the child's name | money for a goal one to five years away (lessons, camp, a first bike) | interest often doesn't keep up with inflation, and the child never sees the money |
| Investment account or managed fund | larger sums for ten years or more, typically from birth to their 18th | the value goes up and down over time; not suited to a short horizon |
| Term deposit in the child's name | a lump sum from grandparents that should sit untouched for a set time | the money is locked away until the term ends |
How to give money so it isn't gone by Monday
Money doesn't vanish because the recipient is careless; it vanishes because it has no name. An amount with no purpose blends into pocket money, and a few days later nobody knows where it went. This approach helps.
- 1Split the amount in advancePut a half or a third towards an instant treat and the rest towards a goal. A child who is allowed to spend something straight away doesn't see saving as a punishment.
- 2Name the goalNot "for something nice", but "for driving lessons", "for a first guitar", "for school camp". A specific goal is harder to fritter away on small purchases.
- 3Hand over the saved part a different wayCash in the card for the treat, the rest by transfer to an account the child doesn't dip into every day. Money that is physically separate doesn't get mixed up.
- 4Add something on paper that lastsA card, a letter or a dedication saying who the money is from and what it's for. In ten years nobody will remember the amount, but a note in your handwriting will turn up in a drawer.
- 5Talk to the parents of a young childWith a child who can't decide for themselves, ask the parents whether they already have an account and what they're saving for. That way the present doesn't end up in the household grocery budget.
When an investment account beats an envelope
An investment account is worth it when three things are true at once: the amount is more than the child would sensibly spend in one go, they won't need the money for at least five and more likely ten years, and someone (a parent or you) is willing to keep an eye on where it goes. The typical case is a christening or birth gift that is meant to wait until adulthood — the topic is also covered in Christening gifts: who gives what and how to avoid doubling up.
For a child under 18, the investment account or fund is usually opened by a parent on the child's behalf. A grandparent or godparent generally can't open one for someone else's child on their own, but they can pay money into it — just agree on the account details with the parents. The money belongs to the child; the parents look after it for them and shouldn't treat it as their own.
Investing doesn't suit money the child needs within two years, small amounts (fees eat into them), or situations where nobody knows who will manage the account. That kind of money is better off in a savings account or in an envelope with a clear goal.
One more thing people overlook: an investment account is invisible to a child. If you don't give them something tangible with it, in ten years they won't know who the money came from. So an investment deserves a keepsake note or a letter — perhaps in a time capsule they open on the day you hand the account over.
How to give money for an 18th birthday
An 18th is a turning point: from the birthday on, they can manage the money themselves, so the present can no longer be "locked away". That makes how you hand it over matter all the more.
- Transfer it to their own account, not an envelopeA large amount of cash at a party is the surest way to lose it. A transfer on the day with a short message in the description feels grown-up and won't go missing.
- Hand over the account you've saved into since birthIf the money has sat for years in an account run by the parents, the 18th is the moment to show them how much has built up and where it came from. It's a present and a lesson at the same time.
- Tie the money to a goal they care aboutDriving lessons, a first car, the bond on a first rental, a language course overseas. A gift "for driving lessons" gets spent on driving lessons; a gift "for something" gets spent on something.
- Add something that lastsMoney gets spent; a card in a drawer stays. Ideas for combining money, words and a keepsake are in 18th birthday gifts for a son, and for a daughter's graduation in A grown-up daughter and her graduation.
What to write with money: messages to copy
A note with money doesn't have to be long. It should say who it's from, what it's for and why now. Here are some lines you can copy or adapt. If you address the card by name, the Australian Government Style Manual adds 's even when the name ends in s: "For Thomas's birthday".
Tax and paperwork: when it matters
For an ordinary present you don't need to worry about paperwork. A birthday or christening gift from family or a godparent is a normal family gesture, not a business deal. If you're handing over a genuinely large sum, check the current rules with an accountant or tax adviser first rather than relying on what someone remembers.
With very large amounts, a simple written record is still worth having: it lets the recipient show where the money came from, for example when they deposit it at the bank or put it towards a home. A short document with both names, the amount, the date and signatures is enough; for a child, a parent signs.
If you'd like to add something that stays after the money is spent, a personal card or a book dedication does the job. A personalised book with the recipient as the main hero carries the dedication right on the first page — it's usually ready online within 15 minutes and costs A$11.99.
Sources
- Australian Government Style Manual — possessive of names: add 's even when the name ends in s ("James's book", "For Thomas's birthday")